• 2026.11.11 (Wed)
  • All articles
  • LOGIN
  • JOIN
Global Economic Times
[등록] 2026-09-01 15:48:31
  • Synthesis
  • World
  • Business
  • Industry
  • ICT
  • Distribution Economy
  • Well+Being
    • Pet Life
    • Halal Horizon
  • Travel
  • Eco-News
  • Education
  • Korean Wave News
  • Opinion
  • Arts&Culture
  • Sports
  • People & Life
    • International Student Report
    • With Ambassador
  • Column
    • Cho Kijo Column
    • Cherry Garden Story
    • Ko Yong-chul Column
    • Kim Bong-seon's Photo Column
    • Kim Seul-Ong Column
    • Lee Yeon-sil Column
  • Photo News
  • New Book Guide
MENU
 
Home > Distribution Economy

South Korean Bank Loan Delinquency Rate Rebounds in January Amid Rising Household and Corporate Defaults

Yim Kwangsoo Correspondent / Updated : 2025-03-28 18:24:43
  • -
  • +
  • Print
Reversal Follows Brief Year-End Dip, Signaling Potential for Continued Upward Trend

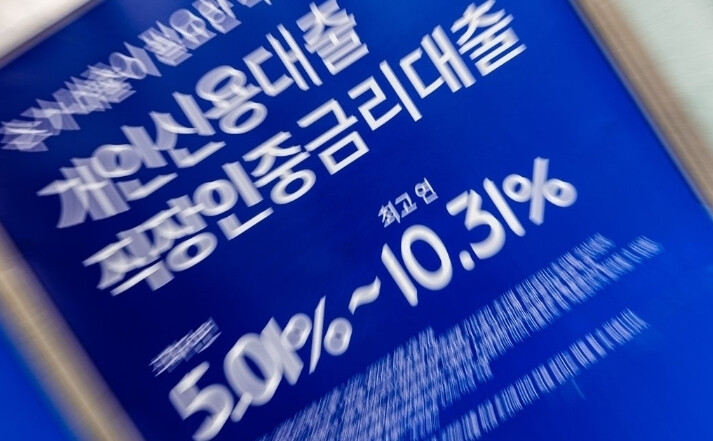
SEOUL, South Korea - South Korean banks experienced a renewed increase in loan delinquency rates in January, according to data released by the Financial Supervisory Service (FSS) on Thursday. The overall delinquency rate for won-denominated loans, defined as principal and interest overdue for more than one month, climbed to 0.53% at the end of January, marking a 0.09 percentage point jump from the 0.44% recorded in December. This reversal comes after a three-month period of increasing delinquency rates was briefly interrupted by a decline at the end of 2024.

The rise in the delinquency rate was fueled by a significant increase in newly overdue loans, which reached KRW 3.2 trillion in January, a KRW 700 billion surge compared to the previous month. Simultaneously, the resolution of existing delinquent loans saw a substantial decrease, falling by KRW 3.3 trillion month-on-month. The new delinquency rate also reflected this trend, rising to 0.13%, a 0.03 percentage point increase from December and returning to the level observed in January of the previous year.

The FSS attributed the January uptick to a "base effect" following the typical year-end decline in delinquency rates, which is often driven by banks intensifying their efforts to clear non-performing loans. However, the significant rise in new delinquencies suggests underlying pressures within the borrowing sectors.

Corporate and Household Loan Delinquencies Both on the Rise

A closer look at the data reveals that both corporate and household loan portfolios contributed to the overall increase. The delinquency rate for corporate loans stood at 0.61% at the end of January, up 0.11 percentage points from the same period last year. While large corporations saw a slight decrease in their delinquency rate (from 0.12% to 0.05% year-on-year), small and medium-sized enterprises (SMEs) experienced a notable increase, with their delinquency rate climbing from 0.60% to 0.77% over the past year. This suggests that smaller businesses may be facing greater financial strain in the current economic environment.

Similarly, the household loan delinquency rate rose to 0.43%, an increase from the 0.38% recorded in January 2024. Both major categories within household lending saw increased delinquency rates: mortgage loans rose from 0.25% to 0.29% year-on-year, and unsecured household loans saw a more significant jump from 0.74% to 0.84% over the same period. This indicates growing challenges for individual borrowers in meeting their debt obligations.

Outlook and Concerns

Despite the recent increase, the FSS noted that the current overall delinquency rate remains below the long-term average of 0.78% observed before the COVID-19 pandemic. However, the fact that the new delinquency rate has returned to the level of January last year raises concerns about a potential sustained upward trend.

"Although the current level is low compared to the long-term average before COVID-19, the new delinquency rate is similar to the level of the same month last year, so the upward trend in delinquency rates is expected to continue for the time being," the FSS cautioned in its statement.

Analysts suggest that factors such as the lingering effects of higher interest rates, coupled with potential economic slowdown, could be contributing to the rising delinquency rates. The increase in both household and corporate defaults warrants close monitoring by financial authorities to assess the potential impact on the stability of the banking sector and the broader economy. Further increases in delinquency rates could necessitate proactive measures from both lenders and policymakers to mitigate risks and support vulnerable borrowers.

[Copyright (c) Global Economic Times. All Rights Reserved.]
  • #globaleconomictimes
  • #글로벌이코노믹타임즈
  • #한국
  • #중기청
  • #재외동포청
  • #외교부
  • #micorea
  • #mykorea
  • #newsk
  • #nammidonganews
  • #singaporenewsk
Yim Kwangsoo Correspondent

Popular articles

  • Chungnam Province Steps Up to Establish Order in Surveying Industry

  • Daewoong Pharmaceutical Builds 'Aseptic Micro-Needle Manufacturing Facility'… Pushing for GMP Approval Next Year

  • Kiwoom Securities: "Growth of Foldable Smartphones to Stand Out... Domestic Beneficiaries"

I like it
Share
  • Facebook
  • X
  • Kakaotalk
  • LINE
  • BAND
  • NAVER
  • https://www.globaleconomictimes.kr/article/1065604991279558 Copy URL copied.
Comments >

Comments 0

Weekly Hot Issue

  • Hyundai Motor Deepens Tech Alliances with Samsung and Nvidia to Pioneer the Physical AI Era
  • G마켓 Expands Beyond Search: E-Commerce Giant Taps Creators for SNS Shopping
  • JTBC Initiates Formal Sale Process to Find a Strategic Buyer
  • Miky Lee Honored with Asian Hall of Fame’s Centennial Medal for Pioneering Global K-Culture
  • The Harsh Reality of K-Pop: Why Small Agency Idols Struggle to Survive Beyond Three Years
  • Regional Tourism in South Korea Struggles as Infrastructure Lags Behind Inbound Airport Growth

Most Viewed

1
US Army Conducts Rare Temporary Burial Drills to Prepare for Worst-Case Large-Scale War Scenarios
2
World Citizens are Flying Directly to Busan... The Era of 4 Million Foreigners is Just Around the Corner
3
Eating 100g of Baechu Kimchi Daily Linked to Lower High-Cholesterol Risks
4
Meeting Christmas Early!… Busan Dessert Sales Event "Daldal The Market" Held
5
South Korea and Ethiopia Sign Trilateral MOU to Introduce Liquid-Based Cytology (LBC) Technology for Cervical Cancer Diagnosis
체리가든 스토리
nutri huevos
로타리
동포저널

Hot Issue

LG Electronics and Skyscanner Partner to Bring Smart Travel Planning to Living Rooms

Regional Tourism in South Korea Struggles as Infrastructure Lags Behind Inbound Airport Growth

Miky Lee Honored with Asian Hall of Fame’s Centennial Medal for Pioneering Global K-Culture

Fashion Runway Show 2026

Let’s recycle the old blankets in Jeju Island’s closet instead of incinerating them.

Global Economic Times
korocamia@naver.com
CEO : LEE YEON-SIL
Publisher : KO YONG-CHUL
Registration number : Seoul, A55681
Registration Date : 2024-10-24
Youth Protection Manager: KO YONG-CHUL
Singapore Headquarters
5A Woodlands Road #11-34 The Tennery. S'677728
Korean Branch
Phone : +82(0)10 4724 5264
#304, 6 Nonhyeon-ro 111-gil, Gangnam-gu, Seoul
Copyright © Global Economic Times All Rights Reserved
  • News K
  • 반달곰 프로젝트
  • 광고문의
Search
Category
  • All articles
  • Synthesis
  • World
  • Business
  • Industry
  • ICT
  • Distribution Economy
  • Well+Being 
    • 전체
    • Pet Life
    • Halal Horizon
  • Travel
  • Eco-News
  • Education
  • Korean Wave News
  • Opinion
  • Arts&Culture
  • Sports
  • People & Life 
    • 전체
    • International Student Report
    • With Ambassador
  • Column 
    • 전체
    • Cho Kijo Column
    • Cherry Garden Story
    • Ko Yong-chul Column
    • Kim Bong-seon's Photo Column
    • Kim Seul-Ong Column
    • Lee Yeon-sil Column
  • Photo News
  • New Book Guide
  • Overseas Koreans
  • Multicultural News