

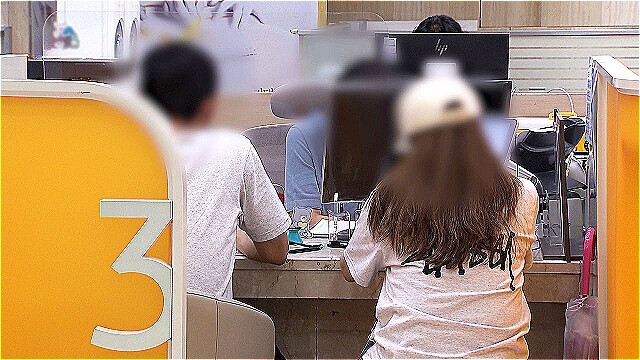
This is the desperate cry of Jeong (32), a job seeker residing in Gwanak-gu, Seoul. Earlier this year, Jeong closed his housing subscription savings account (cheongyak tongjang) which he had diligently maintained for a decade. The payout came out to 10 million won. Having worked at a small-to-medium enterprise from age 28 to 30, Jeong quit to focus full-time on preparing for the civil service exam in pursuit of greater job security. With his living expenses depleted and finding it increasingly difficult to juggle studying and part-time work, he made the difficult decision to surrender his subscription account. "Unemployed and facing an uncertain future, I hated the idea of staying in debt just to hold onto a slim chance at an apartment lottery—a chance that feels virtually nonexistent anyway," Jeong said.
According to the Korea Real Estate Board's subscription portal, Cheongyak Home, the total number of housing subscription account holders dropped from 28.12 million in December 2022 to 25.77 million at the end of July this year—a staggering loss of 2.35 million accounts. The exodus of people in their 30s, the core demographic of actual home buyers, is particularly striking. Data submitted by the Ministry of Land, Infrastructure and Transport to People Power Party lawmaker Jung Hee-yong reveals that the number of canceled subscription accounts among 30-somethings began outpacing new sign-ups starting in 2023 (650,000 cancellations vs. 465,000 new subscriptions). Cancellations continued to exceed new subscriptions through 2024 and 2025. As of July this year, canceled accounts (361,000) outstripped new ones (256,000) by 105,000.
Experts attribute this mass exodus to surging housing prices—marked by Seoul apartment prices rising for 86 consecutive weeks—alongside interest rates on subscription accounts that have remained stagnant at a maximum of 3.1% for two years.
Seoul Apartments: A "Pie in the Sky"
On September 10, Real House, a real estate market research firm, analyzed data from Cheongyak Home and found that as of August, the average price of an apartment in Seoul with a private area of 59 square meters stood at a whopping 1.593 billion won. Given that the entirety of Seoul is designated as a speculative-overheated district, mortgage limits for first-time homebuyers are capped at a maximum of 600 million won. This means that even if someone wins an apartment lottery, they cannot move in unless they have roughly 1.0 billion won in cash on hand.
Kim (33), a corporate worker of four years, also closed his subscription account last month. He felt that the motivation to keep the account had vanished in the face of astronomical pre-sale prices. "Even after working at a sizable company for four years, saving 1.0 billion won—or even 100 million won—is no small feat, and soaring borrowing costs make the interest burden overwhelming," Kim said. "My girlfriend and I agreed to start out in a small villa after we get married the year after next, and we decided it would be wiser to use the money from the subscription account for better wealth-building investments instead."
Parents are also growing increasingly lenient about their children closing these accounts. Choi (50), the parent of a 20-something job-seeking daughter, shared, "Given our current financial shape, we cannot provide substantial financial support for her future home purchase, nor can we continuously cover her living expenses. When she tells me she’s struggling to make ends meet right now, it feels cruel to stop her by blindly insisting she keep the account open for a slim chance at an apartment that may never materialize."
Experts Call for Institutional Overhaul
The relatively low interest rates on subscription accounts have further fueled the cancellation wave, giving even those with no immediate plans to buy a home a reason to pull their money out. Park (26), a senior at Hankuk University of Foreign Studies, pointed to low returns as his primary reason for leaving. "Compared to stocks or regular savings accounts, a 3.1% subscription rate is simply too low," Park said. "Even if people don't open these accounts purely for interest, when winning a lottery is this difficult and the yields are this low, there is no reason to keep them." Indeed, subscription account interest rates rose slightly by 0.3 percentage points from a peak of 2.8% to 3.1% in September 2024, and have remained unchanged ever since.
However, some point out that hiking subscription rates could inadvertently push up policy loan interest rates as well. Policy loans draw their primary funding from the National Housing and Urban Fund, which relies on subscription savings contributions. Raising the interest paid on subscription accounts would increase the fund's procurement costs, potentially driving up loan rates. In 2024, the Ministry of Land, Infrastructure and Transport raised both fund loan rates and procurement rates simultaneously, citing a sharply narrowing margin between them. Yoo Sun-jong, a professor of real estate at Konkuk University, noted, "Instead of using the gap between loan and procurement rates as a shield, times have changed. We need to expand subscription benefits while exploring alternative funding sources for policy loans."
Experts warn that the rising tide of subscription cancellations could widen future wealth disparities, emphasizing the urgent need for systemic reforms. Kim Tae-hoon, head of the Subscription Strategy Research Institute, cautioned, "Given the outsized impact real estate has on wealth creation in South Korea, a surge in account cancellations will only accelerate the wealth gap between a fortunate few winners and everyone else."
Lee Joo-hyun, CEO of Wolcheon Financial Tech and a Ph.D. in real estate, added, "The system must be reformed so that winning a lottery actually translates into successful homeownership. The current point-based system favors middle-aged and older generations with long periods of homelessness and account maintenance, which is out of sync with actual housing demand structures. We need to drastically expand special supply allocations for younger demographics, such as newlyweds in their 30s. Easing balance-payment loan limits and total cap regulations exclusively for winners is another positive direction to enhance the real effectiveness of the subscription system."
[Copyright (c) Global Economic Times. All Rights Reserved.]