

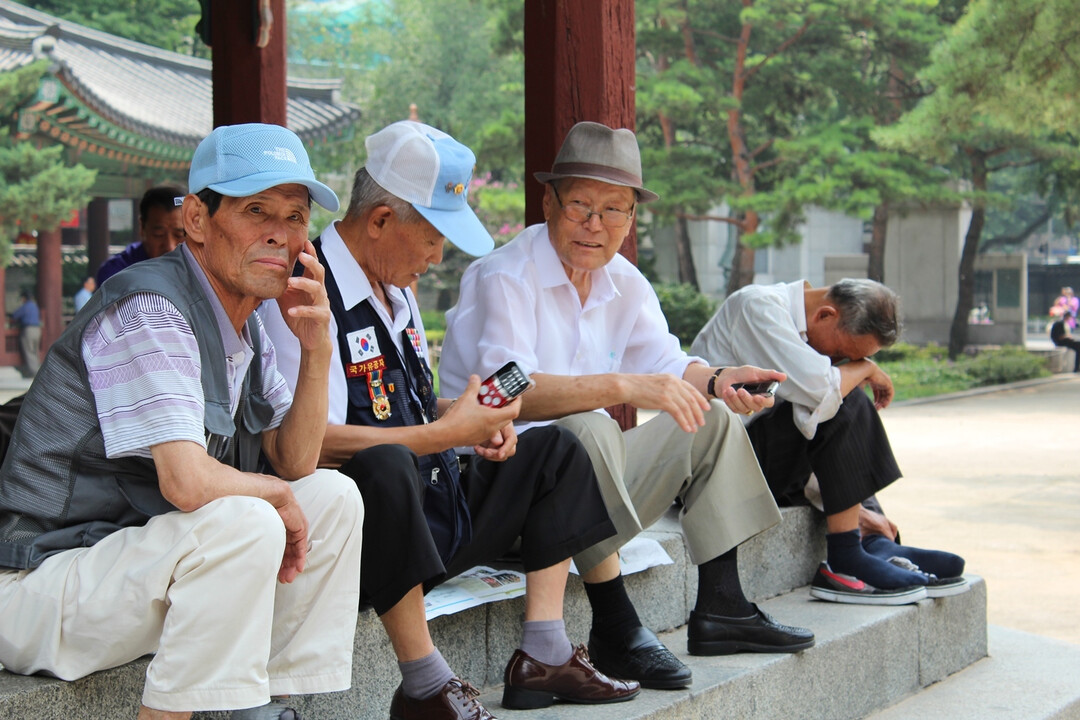
SEOUL — South Korea’s social safety net faces mounting scrutiny as demographic pressures and economic disparities trigger friction between generations. As young workers grapple with prolonged job market contractions and skyrocketing property values, a significant portion of state welfare continues to flow toward affluent senior citizens, intensifying financial strains on the future workforce.
At the core of the debate is the country’s basic pension system, which was originally established to alleviate poverty among older adults. By mandate, the system is designed to cover the top 70% of South Korea's senior population. However, analysts and economists argue that sweeping economic shifts over the past decade have rendered this blanket metric increasingly outdated.
Affluent Seniors Remain Eligible Under Blanket Criteria
With the retirement of the nation’s second baby-boomer generation—individuals born between 1964 and 1974 who benefited from South Korea's rapid economic expansion—the overall wealth of the elderly population has surged. Average senior asset levels now rival the national average. Yet, because the 70% threshold is tied to relative rankings rather than strict financial destitution, the income and property cutoffs for receiving the pension have risen steadily year after year.
Recent data highlights striking examples of this policy mismatch. Government records show that over half of all basic pension recipients own their homes. In high-value metropolitan regions, including Seoul's affluent Gangnam districts, the number of pension recipients has grown by nearly 40% over the last ten years. Current eligibility formulas mean that married couples owning properties valued at well over 1.8 billion KRW (approx. $1.3 million USD) can still qualify for monthly payouts, provided their reported income falls beneath the dynamically adjusted threshold.
A Widening Wealth Chasm for the Young
While older generations enjoy accumulated real estate equity and financial stability, younger South Koreans face a vastly different economic landscape. Youth employment figures have experienced prolonged downturns, and homeownership rates among those in their 30s remain low, hovering around 22%.
Economic data underscores a widening wealth disparity: the net worth gap between households in their 30s and those aged 60 and older has more than doubled over the past decade, expanding from roughly 115 million KRW to over 241 million KRW.
Despite government proposals earlier this year to recalibrate the pension system—shifting focus away from wealthier seniors toward genuinely impoverished elderly demographics—political hesitation and sensitivity surrounding senior voter sentiment led to the suspension of those reforms.
Calls for Structural Overhaul
Experts warn that South Korea’s unique demographic crisis—characterized by simultaneous population decline and ultra-rapid aging—leaves a shrinking base of young taxpayers to shoulder an expanding fiscal footprint.
Policy researchers emphasize that minor adjustments to asset requirements will prove insufficient as long as the rigid 70% rule remains in place. Without comprehensive structural reform to target welfare more precisely toward those in actual financial need, the burden on asset-strapped younger generations will only continue to escalate.
[Copyright (c) Global Economic Times. All Rights Reserved.]