

A recent review of global trade data highlights a widening gap between general commodity prices and soaring energy expenses. Over the past year, import costs for critical energy sources—specifically crude oil and aviation fuel—have skyrocketed by more than 50% to nearly 100%. Although a majority of imported goods have actually seen lower price tags compared to last year, the heavy weight of energy items continues to drive overall import costs upward, raising red flags for consumer inflation.
Energy Takes the Lead While General Imports Soften
According to data released by the Bank of Korea on November 17, the cost of importing crude oil surged by 57.7% year-over-year last month. Other essential industrial energy sources saw similar steep hikes: naphtha prices climbed 45.2%, bituminous coal rose 36.1%, and liquefied natural gas (LNG) advanced 27.2%.
These four categories hold the heaviest weighting within the country's import price index, collectively accounting for 23.1% of the total index value (out of a scale of 1,000). Because these specific commodities carry such massive influence, their sharp appreciation keeps overall import price levels high, even though over 55% of the 237 tracked import items experienced price drops over the same period.
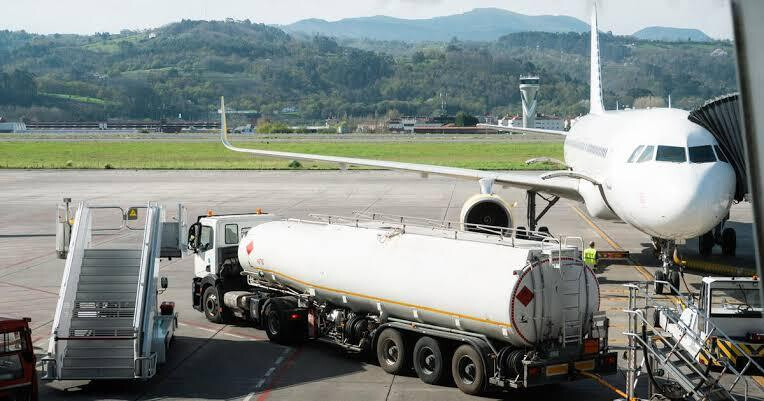
Petroleum derivatives experienced even more dramatic increases. Jet fuel (aviation kerosene) nearly doubled, shooting up 98.1% from a year prior. Bunker-C fuel and diesel also recorded dramatic surges of 82.9% and 81.5%, respectively. Market watchers note that despite a slight month-over-month dip in raw crude prices, refined products like jet fuel and naphtha have continued their upward trajectory for four straight months since July.
The Domino Effect on Consumer Prices
The persistence of high industrial fuel and material expenses places a heavy operational burden on domestic manufacturing and transportation sectors. Economists warn that as companies struggle to absorb these prolonged costs, businesses will eventually have to pass the financial burden down through higher retail and service prices, ultimately putting pressure on everyday consumer inflation with a slight time lag.
Middle East Geopolitics Remain the Ultimate Wildcard
Looking ahead, international energy organizations project a potential easing of global oil prices. The International Energy Agency (IEA) and financial institutions like Goldman Sachs anticipate that global oil markets could transition into an over-supply phase by the final quarter of the year, driven by recovering exports from the Gulf region and cooling demand caused by extended high prices.
However, analysts caution that stability remains fragile. Cumulative global oil reserves have been heavily depleted due to ongoing conflicts, leaving strategic inventories at multi-year lows. Furthermore, any escalation of military friction targeting critical production facilities or maritime shipping routes in the Middle East could instantly derail supply recovery efforts.
While experts suggest that recovering output volumes and subdued demand in certain major economies could eventually help rebuild depleted reserves, persistent security risks mean energy price volatility will likely remain a key economic headwind moving forward.
[Copyright (c) Global Economic Times. All Rights Reserved.]